#754: Fragen und Antworten: Wir haben 80.000 $ in bar und möchten ein 1-2-jähriges Sabbatical. Ist es genug?

Story summary
„In diesen einkommensschwachen Jahren haben Sie diese einmalige Gelegenheit.“ Das habe ich einem Zuhörer gesagt, der mit 80.000 Dollar Bargeld und einem abbezahlten Haus in eine ein- bis zweijährige Karrierepause geht. Reicht das? Es hängt von der einen Zahl ab, die sie uns nicht genannt hat: wie viel sie ausgeben möchte. Also gehen Joe und ich spazieren
📌 Key Highlights & Takeaways
- „In diesen einkommensschwachen Jahren haben Sie diese einmalige Gelegenheit.“ Das habe ich einem Zuhörer gesagt, der mit 80.000 Dollar Bargeld und einem abbezahlten Haus in eine ein- bis zweijährige Karrierepause geht.
- Es hängt von der einen Zahl ab, die sie uns nicht genannt hat: wie viel sie ausgeben möchte.
- Also gehen Joe und ich spazieren
“You have this golden opportunity during these low-income years.” That’s what I told a listener who’s heading into a one-to-two-year career break with $80,000 in cash and a paid-off home.
Is that enough? It depends on the one number she didn’t give us: how much she plans to spend.
So Joe and I walk through how to set aside what the sabbatical needs from a $394,000 taxable brokerage account, why a career break is the perfect window for Roth conversions, and whether an all-stock portfolio is too risky in your 30s.
Before we get there, we help a listener in the UK who wants to fund a career break, travel, and home projects while her emergency fund is only half built, and who’s wondering whether she has to finish one before starting the others. We close with something we rarely touch on this show: how to judge whether a politician is actually good for the economy.
Listen on Apple Podcasts Listen on Spotify Watch on YouTube
Anonymous (let’s call them “Amelia”) asks: How would you define the difference between an emergency fund, sinking funds (such as for a new laptop), and medium-term savings (like a career break or a big trip within the next two years)? How should we think about and treat these pots differently, and is there a defined line or overlap between them? Additionally, some people replace the term emergency fund with opportunity fund, which adds another dimension.
Secondly, how do you create a structure to decide how to apportion discretionary money across competing goals? How should someone choose which pot or goal to prioritize or allocate the largest contribution to, versus funding each pot equally?
For context, I am 42 and based in the UK. My defined contribution pension—similar to a 401(k)—can be accessed around age 57, and with my current contributions, I expect to retire at 64. My goal is to have an eight-month emergency fund, and I currently have four months saved. I would like to start funding other goals, such as a career break, travel, and home improvements, alongside building my emergency fund. Can I start funding those other pots now, or should the emergency fund be fully funded first? Once the emergency fund is taken care of, at what point should I pivot back to bringing my retirement age forward versus funding adventures over the next two decades? How should I balance multiple goals across differing timelines and magnitudes, weighing the flexibility of cash savings against the growth of investing?
Editorial Text & Content Analyzer
Analyze real-time word count, reading speed, and text density metrics on the fly.
Source: Afford Anything®.
Read the full story at the original source ↗
For questions: mrsmithcons@gmail.com.
❓ Frequently Asked Questions (FIRE Strategies Briefing)
How does this FIRE Strategies strategy accelerate financial independence and compounding?
By focusing on high-margin micro-acquisitions, zero-capital bounties, and automated digital toolkits, cash flow can be systematically reinvested without taking unhedged downside risk.
What is the optimal capital allocation and safe withdrawal threshold?
FIRE models recommend maintaining a 3.5% to 4.0% safe withdrawal rate (SWR) with at least 12 months of liquid operational reserves while scaling automated digital assets.
What execution tools are recommended for replicating these results?
Explore our verified directory of open-source scripts, micro-SaaS evaluation checklists, and vetted bounty platforms linked across FreeRich FIRE.
📈 Complete FIRE Early Retirement Dossier & Models
Asset allocation breakdowns, safe withdrawal rate math, and tax optimization hacks.
⚡ Access FIRE Dossier ➔More from FreeRich FIRE
 🐋 CryptoAce VIP
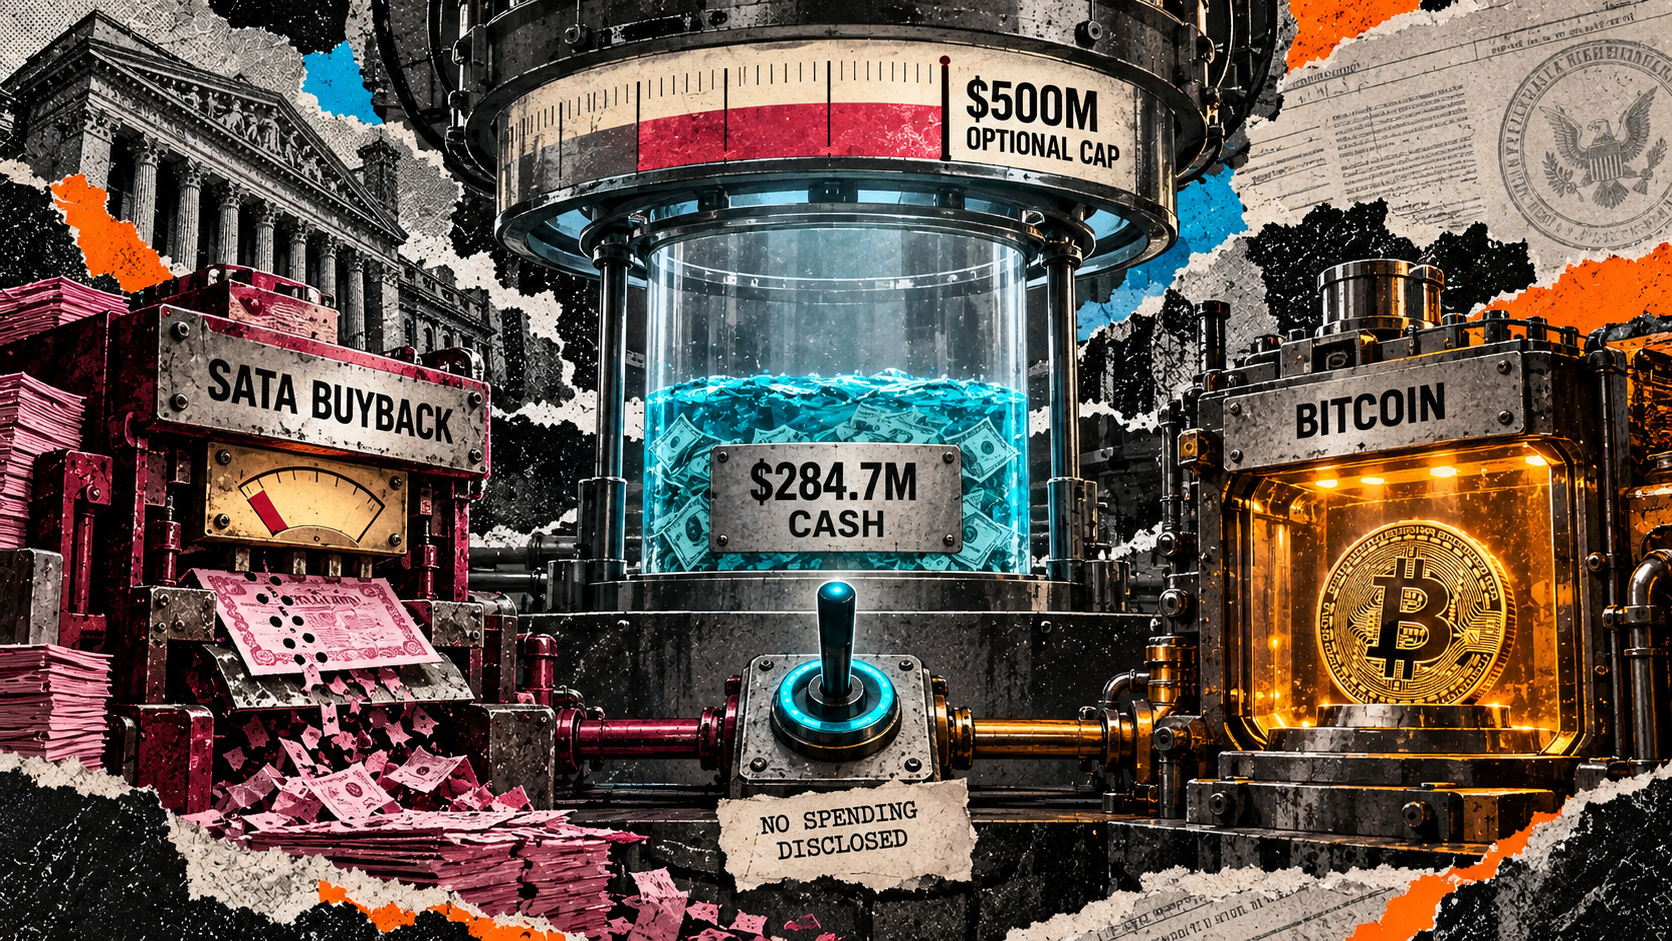
Bitcoin Treasury Strive riskiert Bargeldreserven, um Rückkäufe in Höhe von 500 Millionen US-Dollar zu finanzieren und Dividenden zu kürzen
Die optionale SATA-Obergrenze beträgt 215,3 Millionen US-Dollar über den Barmitteln vom 2. Oktober, ohne dass ...
 ⚡ LiveCoin Bet
Crypto Casinos 2026 - JACK Highlights Market Trends with Instant Crypto Cashout Features
Breaking coverage reported by The Manila Times: Crypto Casinos 2026 - JACK Highlights Market Trends with Insta...
 🎁 Get Rich Free
Wesentliche Blaupause: Wie Führungskräfte im Jahr 2026 mit kostenlosen Bargeldprämien für eine ertragsstarke Leistung umgehen
Umfassende redaktionelle Analyse für 2026, die sich mit kostenlosen Bargeldprämien bei „Get Rich Free“ befasst...
Dead-End Job Teaser Turns a Side Hustle Into a Nightmare on Netflix
The money is good. The jobs are strange. And there’s definitely a catch. Drowning in debt, a young man turns t...